By Amy Walker
Dominic Konieczny, manager of market analytics, contributed to this report.
Eastern Europe has matured into a mid-cost, high-quality talent region where workforce strategy must be increasingly selective, specialised and location-sensitive. While Poland and Romania remain core hubs for scale, other markets across the region offer targeted advantages for niche skills, cost optimisation or operational resilience.
Recent Allegis Global Solutions’ (AGS) findings show that the market is defined by intensifying competition for digital and technical talent, longer hiring cycles, rising candidate expectations and growing operational complexity. As a result, organisations can no longer rely on cost arbitrage or single-country sourcing strategies alone; success increasingly depends on faster decision-making, proactive workforce planning and a diversified multi-country location strategy aligned to business priorities.
AGS Market Insights on Eastern Europe’s Talent Landscape
Across Eastern Europe, hiring demand is becoming increasingly specialised, selective and aligned to critical business priorities rather than volume-based hiring. Organisations are prioritising high-impact digital and transformation roles, with particularly strong demand for Cloud (AWS, Azure, GCP), artificial intelligence, data, cybersecurity and advanced software engineering capabilities. At the same time, the region continues to support growth in shared services and corporate functions, particularly in finance and multilingual support roles, reinforcing its dual position as both a technical and operational delivery hub.
Labour markets across Central and Eastern Europe remain tight and increasingly candidate-driven, particularly in core markets such as Poland, the Czech Republic and Bulgaria, where unemployment levels are low, and competition for talent is high. This has led to consistent salary growth (typically 5–10% annually for in-demand skills), longer hiring cycles and a rise in counteroffers. Candidates are frequently managing multiple opportunities simultaneously, with decision-making influenced by factors such as remote flexibility, access to modern technologies, career progression and long-term project stability rather than compensation alone.
A clear evolution in operating models is also evident. Organisations are shifting away from single-country, cost-led strategies towards multi-country, hub-and-spoke delivery models, where Poland and Romania act as core hubs for scale and markets such as Bulgaria, Hungary and the Baltics provide cost optimisation or niche capabilities. This is reinforced by increased adoption of nearshoring and distributed team models, supported by strong time zone alignment with Western Europe and growing acceptance of remote work. In parallel, there is a noticeable shift towards outcome-based and SOW delivery models, as organisations prioritise quality, flexibility and long-term value over purely cost-driven engagements.
However, organisations must navigate increasing operational complexity, including persistent talent shortages in niche skill sets, high levels of competition and counteroffers, complex labour laws (including B2B versus employment models) and extended notice periods — often up to three months. These factors are making speed, workforce strategy and market intelligence critical to successful hiring outcomes in the region.
Supplier Insights on Workforce Planning Across Eastern Europe
From a supplier perspective, the Eastern European market is not simply growing or declining — it is becoming more fragmented, competitive and location-sensitive, requiring a more strategic and forward-looking approach to workforce planning. Hiring demand varies significantly by country and skill set. However, a consistent theme is that access to talent is becoming increasingly constrained, particularly in digital and hybrid roles that combine technical expertise with regulatory or business knowledge.
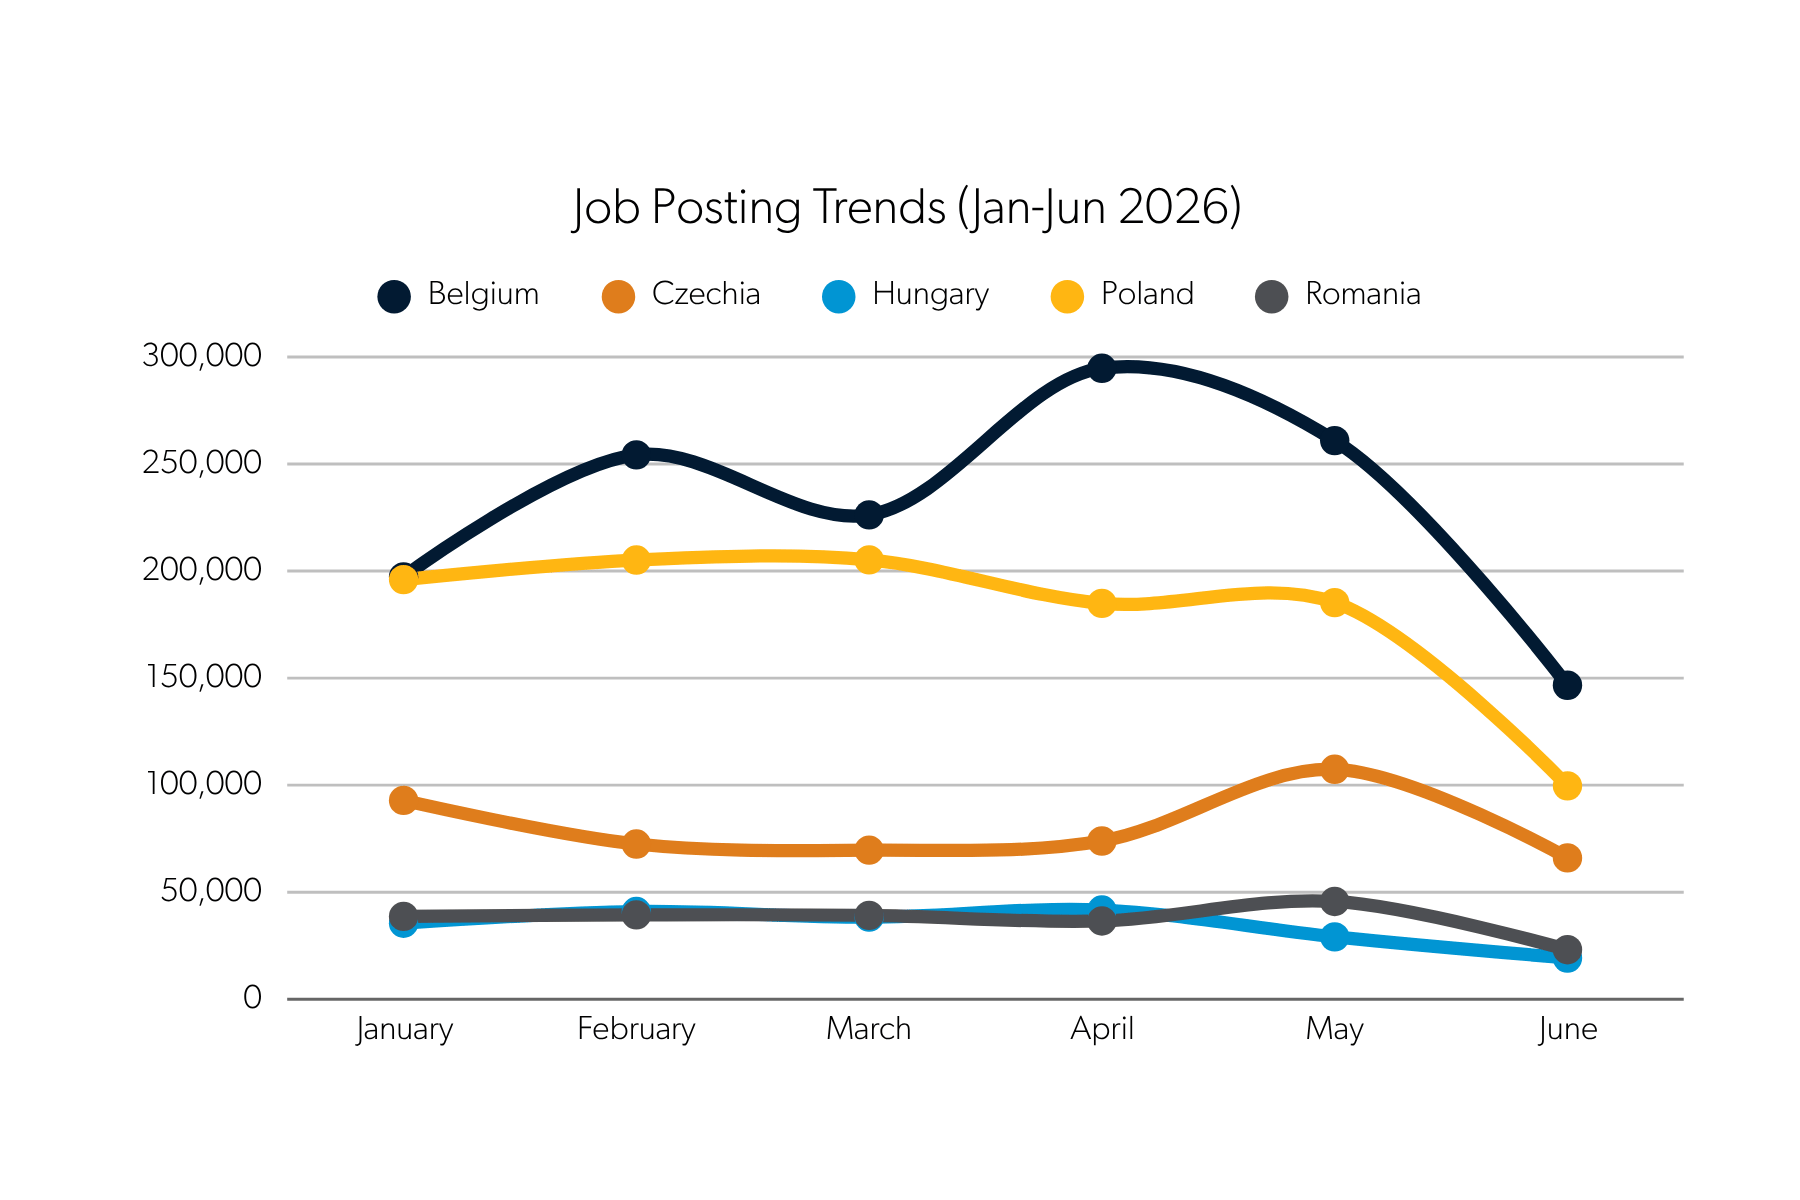
Suppliers highlight that organisations are experiencing intensifying competition for high-value talent, driven by continued investment in digital transformation and research-led capabilities. This is placing pressure on already limited talent pools and reinforcing the need for earlier pipeline development, proactive talent mapping and upskilling strategies.
Workforce planning can no longer rely solely on current demand; instead, organisations must adopt a forward-looking approach that anticipates future skill gaps and evolving capability requirements.
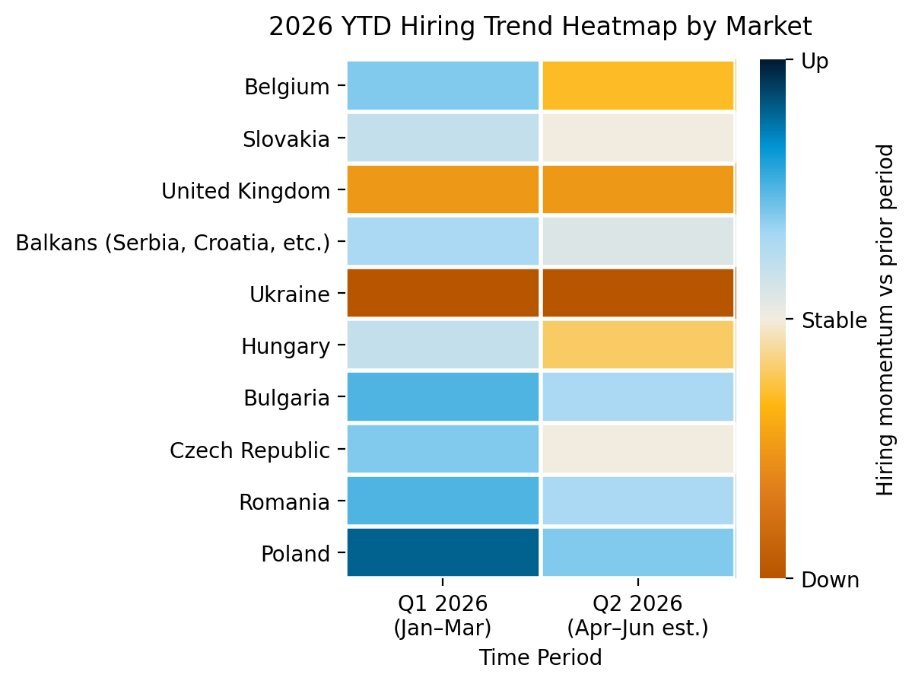
Another key theme is the growing complexity of hiring across the region. While cost efficiency remains relevant, it is no longer the primary decision driver. Organisations must now consider a broader set of factors, including regulatory requirements, pay transparency legislation, labour market dynamics, workforce participation trends and infrastructure maturity. These variables directly impact supplier delivery models, scalability and overall hiring speed, making local expertise and well-designed operating models essential.
Suppliers also emphasise that location strategy is becoming a critical lever for success. Traditional single-country approaches are increasingly being replaced by integrated, multi-location capability models, where different markets are selected for their specific strengths— whether that is scalability, cost efficiency or specialised skills. These models are not just about cost arbitrage, but about building resilient, capability-driven delivery networks aligned to global business priorities.
Key Findings on Eastern Europe’s Evolving Talent Market
Bringing together both AGS and supplier perspectives, Eastern Europe has clearly transitioned into a mid-cost, high-value talent region where complexity, competition and capability depth define success. The market is no longer characterised by easy access to low-cost talent; instead, organisations must balance cost, quality, speed and risk through carefully designed, multi-country strategies.
Success in this environment requires a combination of faster hiring processes, stronger employer value propositions, proactive workforce planning and diversified location strategies. Organisations that continue to rely on traditional, single-market or cost-led approaches are increasingly exposed to talent shortages, hiring delays, and delivery risks. In contrast, those adopting integrated, multi-market and capability-driven models are better positioned to secure talent, manage complexity and sustain long-term growth across the region.
Country Snapshots of Key Eastern European Markets
The following snapshots show how talent availability, cost, scalability and operational considerations vary across key Eastern European markets.
Poland
As the region’s strongest hub, Poland continues to see sustained demand alongside rising costs and competition.
Most common skill sets:
- Software engineering / developers
- Cloud engineers (AWS, Azure, GCP)
- Data / AI / ML specialists
- Cybersecurity professionals
- DevOps / SRE
- Shared services (finance, HR, support)
Romania
As a growing hub, Romania offers a strong cost-to-quality balance and scalability.
Most common skill sets:
- Software developers
- QA / testing
- Cybersecurity
- IT support / support engineering
- Shared services / BPO roles
- Multilingual service roles
Czechia
As a high-value market, Czechia is constrained by severe labour shortages.
Most common skill sets:
- ERP specialists (e.g., SAP)
- Engineering (especially manufacturing and automotive)
- Project managers
- IT specialists / enterprise systems
- R&D roles
Hungary
As a stable SSC hub, Hungary’s market offers moderate growth and complexity.
Most common skill sets:
- Finance and accounting
- Procurement / supply chain
- Business intelligence
- SAP / ERP specialists
- SSC / shared services roles
- Multilingual customer / service roles
Bulgaria
As a cost-effective market, Bulgaria is limited by a smaller talent pool.
Most common skill sets:
- DevOps engineers
- QA / testing
- Backend developers
- Software engineers
- IT / technical support
- BPO / contact centre roles
Balkans
As emerging markets, the Balkans offer cost benefits but limited scale.
Most common skill sets:
- Software developers
- Engineering (backend / DevOps)
- IT outsourcing roles
Ukraine
Despite offering high-quality talent, Ukraine carries operational risk due to ongoing conflict.
Most common skill sets:
- Software developers
- Engineers (general and specialised)
- IT / technical roles (remote)
Turning Market Intelligence Into Workforce Strategy
Together, these findings underscore the need for organisations to move beyond broad regional assumptions and take a more informed, market-specific approach to workforce planning in Eastern Europe. Developed by our market analytics team, the report draws on AGS’ market intelligence and supplier performance data from more than 120 contingent workforce programmes, along with intelligence from AGS’ Acumen® Intelligent Workforce Platform, external labour market data and qualitative input gathered from AGS’ European supplier community.


 By Simon Bradberry
 By Renee Gorman